VAT
Do I Have to Register for VAT?
· 3 min read
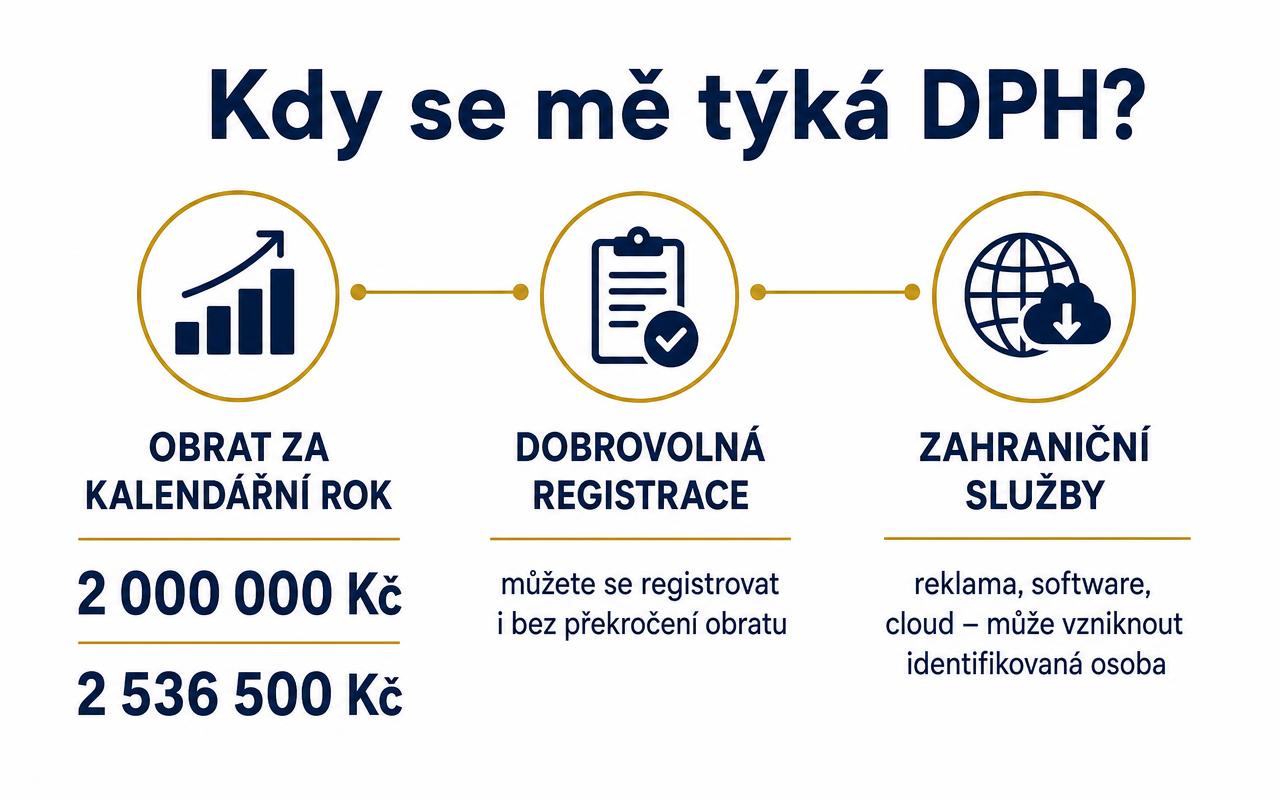
You register for VAT either after exceeding the legal turnover threshold or voluntarily. A separate category is an identified person (identifikovaná osoba), which many entrepreneurs overlook when purchasing services from abroad.
Short answer
IT DEPENDS
Registration is mandatory after exceeding the statutory turnover threshold for the monitored period. However, regardless of turnover, you become an identified person upon your very first purchase of a service from a supplier in another EU member state.
Quick take
- The decisive factor is your turnover for the last 12 consecutive calendar months.
- You must submit your registration application within 10 days after the end of the month in which you exceeded the turnover threshold.
- You become an identified person even without exceeding turnover — typically when purchasing advertising or software from abroad.
- Voluntary registration pays off if most of your clients are VAT payers and you have substantial business expenses (inputs).
Mandatory Registration Based on Turnover
Turnover is defined as the total sum of consideration excluding tax for taxable supplies with a place of supply in Czechia. You track this on a rolling basis over the past twelve consecutive months, not by calendar year. Once you exceed the threshold, you must submit a registration application and become a full VAT payer as of the date specified by law. From that moment, you issue invoices including VAT and submit both VAT returns and VAT control statements (kontrolní hlášení).
Identified Person — The Most Common Oversight
You become an identified person (identifikovaná osoba) when you receive a service with a place of supply in Czechia from a business registered for VAT in another EU member state (e.g. social media advertising, cloud software tools, marketplace commissions), or when you acquire goods from the EU above the statutory threshold. An identified person does not charge VAT on domestic sales and cannot claim input VAT deductions, but must declare and pay tax on received cross-border services and file a VAT return for the month in which the supply occurred.
When Voluntary Registration Makes Sense
Voluntary registration is worthwhile if your customers are predominantly VAT-registered businesses and you incur significant expenses subject to VAT — such as commercial rent, materials, equipment, or subcontracting services. Conversely, if your customers are end consumers (B2C), VAT registration generally means either higher prices for your clients or lower profit margins for you.
Administrative Requirements of VAT Registration
A full VAT payer must file regular VAT returns, VAT control statements (kontrolní hlášení), and, in the case of cross-border transactions, recapitulative statements (souhrnné hlášení). All filings must be submitted electronically and strictly within statutory deadlines. Invoicing requirements also become stricter: without tax documents containing all legally required details, you cannot claim input tax deductions.
What to do now
- 1Calculate your turnover for the last 12 months and monitor it on a monthly rolling basis.
- 2Check whether you purchase services from abroad — if so, register as an identified person.
- 3If you exceed the turnover threshold, submit your registration application within 10 days after the end of that month.
When to call an accountant
Before your first purchase of a service from abroad, when selling goods cross-border, or when considering voluntary VAT registration.
Frequently asked questions
- Does the sale of business assets count towards the turnover threshold?
- The sale of fixed assets is generally excluded from the turnover calculation, whereas regular sales of goods and services are included. For borderline cases, we recommend consulting a tax advisor.
- Does an identified person have to submit a VAT control statement (kontrolní hlášení)?
- No, an identified person does not submit a VAT control statement. They only submit a standard VAT return for the tax period in which a tax liability arose.
- Can VAT registration be cancelled?
- Yes, once statutory conditions are met and the required minimum period from registration has elapsed. Keep in mind that input tax deductions on retained assets may need to be adjusted.
Sources
Author: FinTaxo expert team
Operated by: Zaklipso s.r.o.
Information valid as of: 17 August 2026
Czech original: read this article in Czech
This article is general information and does not replace individual tax, accounting or legal advice. Czech legislation changes frequently — verify the current wording or discuss your situation with us before acting on it.
Need help with this in practice?
We go through your situation in a free consultation in English and tell you exactly what has to be registered, filed and paid.
Czech accounting news, once a month
Practical updates on Czech taxes, VAT and payroll — concise and spam-free. Unsubscribe anytime.
By subscribing you consent to the processing of personal data under GDPR and to their use for the marketing purposes of FinTaxo, operated by Zaklipso s.r.o.. You can withdraw your consent at any time. See our privacy policy.